How to increase your Scapia Credit Card limit: the in-app upgrade flow, email request method, what the bank looks for, timelines, and common mistakes.
Apply for the Scapia Credit Card
Zero Forex Markup on international spends, unlimited domestic lounge access, and Lifetime Free guarantee.
Got a lower limit than you expected on your Scapia Credit Card? You are not alone – and you are not stuck with it. Limits on this card are reviewed periodically by the issuing bank, and there are two realistic ways to get an increase: accept a pre-approved upgrade when the app offers you one, or proactively request a review with fresh income proof.
This guide covers both methods step by step, what the bank actually looks for, how long it takes, and the mistakes that keep limits frozen.
The Short Answer: Your Two Paths to a Higher Limit
- Path 1 – Pre-approved upgrade (easiest): The bank periodically reviews accounts and pushes limit upgrade offers into the Scapia app. When you see “Your credit limit upgrade is ready,” you can accept it in under a minute with your M-PIN. No documents, no waiting, no extra inquiry.
- Path 2 – Manual request: Email the bank’s credit card support (the address on your statement or in the app), attach recent income proof such as payslips or ITR, and ask for a limit review.
- What will not work: There is no “request increase” button to tap on demand, no published formula, and no guaranteed approval. The bank decides at its sole discretion.
New to the card? Our eligibility guide explains how initial limits are set in the first place.
How Scapia Decides Your Limit (What the Agreement Says)
The cardholder agreement is refreshingly blunt about this. The key points, in plain language:
- The bank determines your credit limit at its sole discretion and notifies you of it.
- The bank may review the limit from time to time, on its own or at your request, and increase or decrease it based on your eligibility at that point.
- You can also request a lower limit if you want tighter control over spending.
- Your limit and available credit appear on every monthly statement.
Translation: limit increases are a privilege the bank grants based on how you behave as a customer, not a right you can demand on a schedule. Everything in the next sections flows from that reality.
Method 1 – Accept the Pre-Approved Upgrade in the App
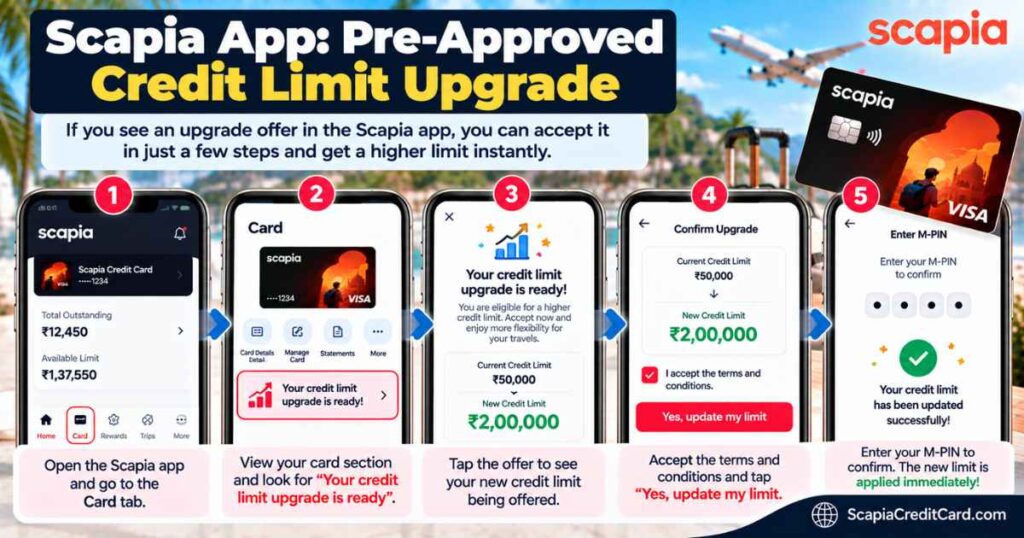
This is how most Scapia limit increases actually happen. When the bank’s periodic review flags your account as eligible, the offer appears in the app. Here is the exact flow:
- Download Scapia App.
- Open the Scapia app and log in.
- Go to the Card tab.
- Look for the message “Your credit limit upgrade is ready” below the quick-action options. If it is not there, no offer is currently available for you.
- Tap the message to view the new limit being offered.
- Tick “I accept the terms and conditions” and tap “Yes, update my limit.”
- Enter your M-PIN to confirm. The new limit is applied to your card immediately.
There are no extra fees for the upgrade, and because the bank has already approved it, there is no fresh application or waiting period. Check the app periodically – offers appear after review cycles, not on request.
Method 2 – Request a Limit Review by Email
If no in-app offer has appeared and you believe your profile now supports a higher limit (a salary hike, for example), you can ask for a manual review:
- Find the credit card support email – it is listed on your monthly statement and in the app’s help section. Use the channel tied to your issuing bank (Federal Bank, Axis Bank, or Bank of Baroda).
- Write a short request with your name, registered mobile number, and card details (never share your full card number, CVV, or OTP – support will never ask for these).
- Attach income proof: the last 2-3 months’ payslips or your latest ITR/form 16 for salaried applicants; ITR and bank statements for self-employed applicants.
- State the reason briefly – e.g., income has increased since the card was issued, or current limit constrains regular travel bookings.
- Wait for the review. The bank will assess your repayment history, utilisation, and credit profile before deciding.
A manual request may involve a fresh look at your credit report. It is not guaranteed, and there is no published turnaround time – allow a few weeks before following up once.
What Actually Gets Your Limit Increased
| Factor | Why it matters | What “good” looks like |
|---|---|---|
| Repayment history | The single biggest signal. Missed or late payments are the fastest way to freeze your limit. | Every bill paid in full, on or before the due date, for 6-12 months. |
| Credit utilisation | High utilisation suggests you are stretched; low utilisation suggests headroom. | Keep usage under 30% of your limit in most months. |
| Card usage and tenure | An unused card gives the bank no data to justify more credit. | Regular monthly usage for at least 6 months. |
| Income growth | A higher income supports a higher limit – but only if documented. | Updated payslips or ITR showing growth since issuance. |
| Overall credit score | The bank re-checks your profile during reviews. | Stable or improving CIBIL, ideally 750+. |
| Other bank relationships | Heavy borrowing elsewhere raises your risk profile. | Manageable total debt across all products. |
Notice what is not on the list: how often you ask. Repeated requests do not help; demonstrated behaviour does.
The 30% Utilisation Rule, With Numbers
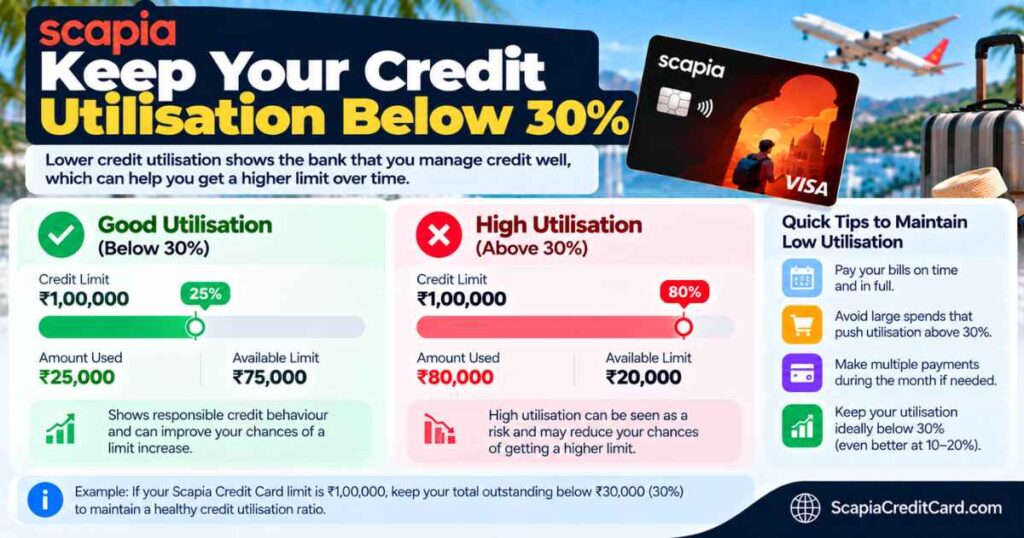
Credit utilisation is the percentage of your limit you actually use. It is one of the strongest inputs to both your credit score and the bank’s limit decisions. Here is how it plays out:
- Rs. 1,00,000 limit, Rs. 25,000 monthly spend: 25% utilisation – healthy. This profile gets upgrades.
- Rs. 1,00,000 limit, Rs. 80,000 monthly spend: 80% utilisation – the bank reads this as strain, even if you pay in full. Upgrades stall.
- Rs. 50,000 limit, Rs. 45,000 monthly spend: 90% utilisation – high risk signal. Pay down balances and bring this under 30% for a few cycles before expecting any increase.
The paradox: the people who most need a higher limit (because they constantly max out a small one) look the riskiest. The fix is to pay down mid-cycle – you can pay your card bill more than once a month – keeping reported utilisation low while still spending what you need. Our bill payment guide covers the mechanics.
Realistic Timelines: When to Expect an Increase
- First 6 months: unlikely. The bank wants a track record. Focus on perfect payments and sub-30% utilisation.
- 6-12 months: the realistic window for the first pre-approved offer, assuming clean behaviour and regular usage. Cardholders report upgrades appearing in the app after sustained healthy usage in this band.
- After 12+ months: if nothing has appeared despite good behaviour, a manual email request with fresh income proof is reasonable.
- After a salary hike: update your income proof and request a review – this is the single strongest trigger for a manual increase.
There is no fixed schedule and no entitlement. Two cardholders with identical behaviour can get offers months apart – the review cycles are the bank’s, not yours.
Know Your Sub-Limits: Cash Withdrawals and Overlimit Charges
Your headline credit limit is not the only number that matters:
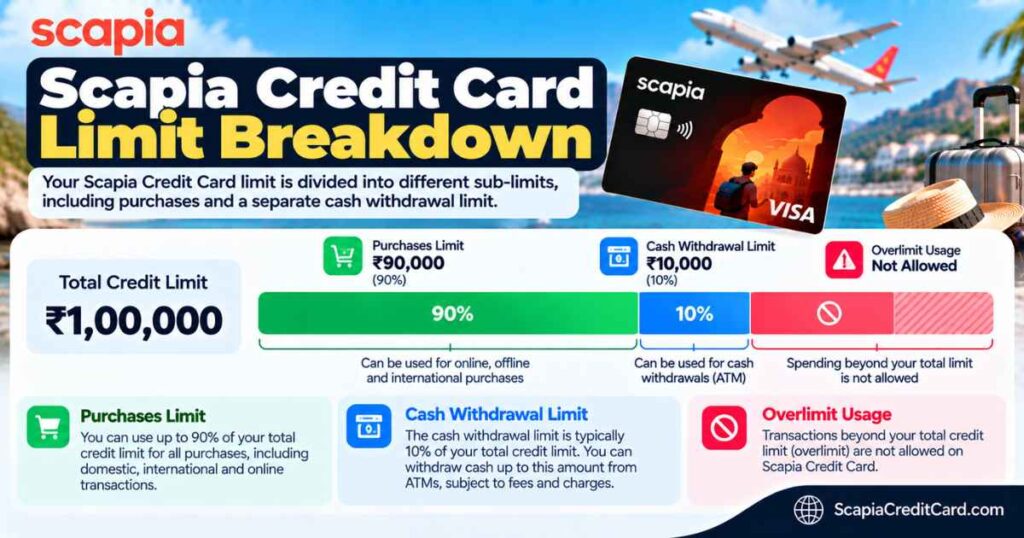
- Cash withdrawal limit: 10% of your credit limit. On a Rs. 2,00,000 limit, you can withdraw at most Rs. 20,000 in cash. Cash advances also attract interest from day one (around 3.49% per month) plus a withdrawal fee – they are the most expensive way to use the card. See our ATM withdrawal charges guide before you ever do this.
- Overlimit charges: 2.5% of the overlimit amount, minimum Rs. 500. Exceeding your limit is possible on some transactions but punished – another reason to keep utilisation well below 100%.
- Minimum amount due: 5% of purchases plus 100% of any overlimit amount, EMIs due, and charges. Paying only the minimum keeps the account “current” but interest on the rest runs at about 41.88% per annum – full payment is the only sensible habit.
- Until the physical card arrives, usage may be limited to online transactions and a portion of the limit – the full limit unlocks with the physical card.
Mistakes That Stall Your Limit Growth
- Paying only the minimum due. It avoids a late fee but signals financial stress and piles up interest.
- Missing a due date even once. A single 30-day late mark can freeze limit reviews for a year or more.
- Running utilisation near 100% every month. Looks like distress, even when paid in full.
- Letting the card sit unused. No usage data means no case for a higher limit – and remember, 365 days of inactivity wipes your Scapia Coins too.
- Applying for multiple credit products at once. Each inquiry dings your profile right when the bank is evaluating you.
- Requesting increases every month. It does not speed anything up and can look desperate in manual reviews.
What Is the Maximum Scapia Credit Card Limit?
There is no published maximum. The bank does not advertise a ceiling, and the agreement leaves the figure entirely to its discretion. Cardholders publicly report limits ranging from Rs. 50,000 on starter profiles to Rs. 5 lakh and above on strong profiles, with some applicants shown limits of Rs. 10 lakh at approval.
Treat those numbers as data points, not targets. Your limit is a function of your income, credit history, and behaviour – not of what someone else received. And a higher limit is only useful if your spending justifies it: a Rs. 5 lakh limit you never use above Rs. 40,000 is just a number on a statement. If travel spending is what you are scaling up, the zero forex markup and lounge benefits are where the card earns its keep regardless of limit.
Frequently Asked Questions
-
How can I increase my Scapia Credit Card limit?
Two ways: accept a pre-approved upgrade when the Scapia app shows “Your credit limit upgrade is ready” (Card tab, confirm with M-PIN), or email the bank’s credit card support with recent income proof and request a manual review. Approval is at the bank’s discretion in both cases.
-
Does Scapia offer pre-approved limit increases?
Yes. The bank periodically reviews accounts and pushes upgrade offers into the app. There is no fixed schedule – offers appear after review cycles, typically after 6-12 months of healthy usage.
-
How long should I wait before requesting a limit increase?
Give it at least 6 months of on-time full payments and regular usage. The strongest position is 12 months of clean history, or a documented income increase at any point.
-
What is the maximum credit limit on the Scapia Card?
There is no published maximum. Limits are set at the bank’s sole discretion based on income, credit history, and account behaviour. Reported limits range from Rs. 50,000 to Rs. 5 lakh and above.
-
Will requesting a limit increase hurt my credit score?
Accepting a pre-approved in-app upgrade does not require a new application. A manual email review request may involve the bank re-checking your credit profile, which can mean a hard inquiry. Either way, the bigger score factor is your ongoing utilisation and payment behaviour.
-
What is the cash withdrawal limit on the Scapia Credit Card?
10% of your credit limit. Cash withdrawals also attract interest from day one plus a withdrawal fee, making them the most expensive transaction type on the card.
-
Can my Scapia credit limit be decreased?
Yes. The cardholder agreement explicitly allows the bank to increase or decrease your limit at its discretion during periodic reviews – for example after missed payments or a deteriorating credit profile.
-
Why was my limit increase request declined?
The usual reasons: short account tenure, high utilisation, missed or minimum-only payments, no documented income growth, or a weakened overall credit profile. Fix the underlying factor, wait a few months, and the next review cycle is a fresh chance.